Usually not, and here is why
Most of the time, no. We tell people that on the phone before they get their hopes up, because the disappointment is worse coming later. The deciding factor is almost never the mold itself. It is the water that came before it. A policy will often pay for mold that followed a sudden, accidental, covered water loss, and even then only up to a cap. Mold that grew slowly, from humidity, from a long slow leak, or from something that needed maintenance, is excluded on nearly every policy written. This page is how to tell which one you have before you spend a phone call finding out.
Peak Performance Restoration is a restoration contractor. We are not attorneys and we are not licensed public adjusters. Nothing on this page is legal advice or a coverage opinion on your policy. Your carrier decides coverage, and the language in your policy is the language that governs.
How mold coverage is decided
Coverage follows the cause of the water, not the mold. Insurance adjusters do not evaluate mold. They evaluate the water event that produced it, decide whether that event is covered, and then apply whatever mold language the policy carries on top of that decision.
That is why two houses with identical growth on identical drywall get opposite answers. One had a supply line let go on a Tuesday. The other had a shower pan weeping for three years. Same mold, same scope, same price. Different cause of loss.
So the first question on a mold claim is never how bad is it. It is what made this wet, when did it start, and can that be documented. We answer those three in writing, honestly, whichever way the answer falls.
Which side of the line your water is on
Written as most policies read, not as yours reads. The declarations page and the endorsement list on your own policy are what govern.
Usually covered
- A supply line, a hose, or a fitting that failed suddenly, and the mold that followed before the drying was finished.
- A water heater that let go.
- A dishwasher, washing machine, or refrigerator line that burst rather than seeped.
- Storm damage that opened the building: wind-lifted shingles, a tree through the roof, a window broken by debris, and the water that got in through it.
- An ice dam that forced water back under the roofing and into the attic or the ceiling, on many policies.
- A frozen pipe that split, provided the house was heated or properly winterized. Most policies exclude freeze damage in a home left unheated without the water shut off and drained.
- Sewer or drain backup, but generally only if a backup endorsement was added to the policy. It is not standard coverage on most homeowner forms.
Usually not covered
- Mold from long-term humidity: a damp crawlspace, a bathroom with no working fan, a bath fan ducted into the attic.
- A leak that dripped for months or years. Most policies call this continuous or repeated seepage and exclude it by name.
- Ground water and surface water. This is flood, and flood is excluded on essentially every standard homeowner policy.
- Deferred maintenance: a roof past its life, failed caulk at a tub surround, a gutter that has been discharging at the foundation since 2019.
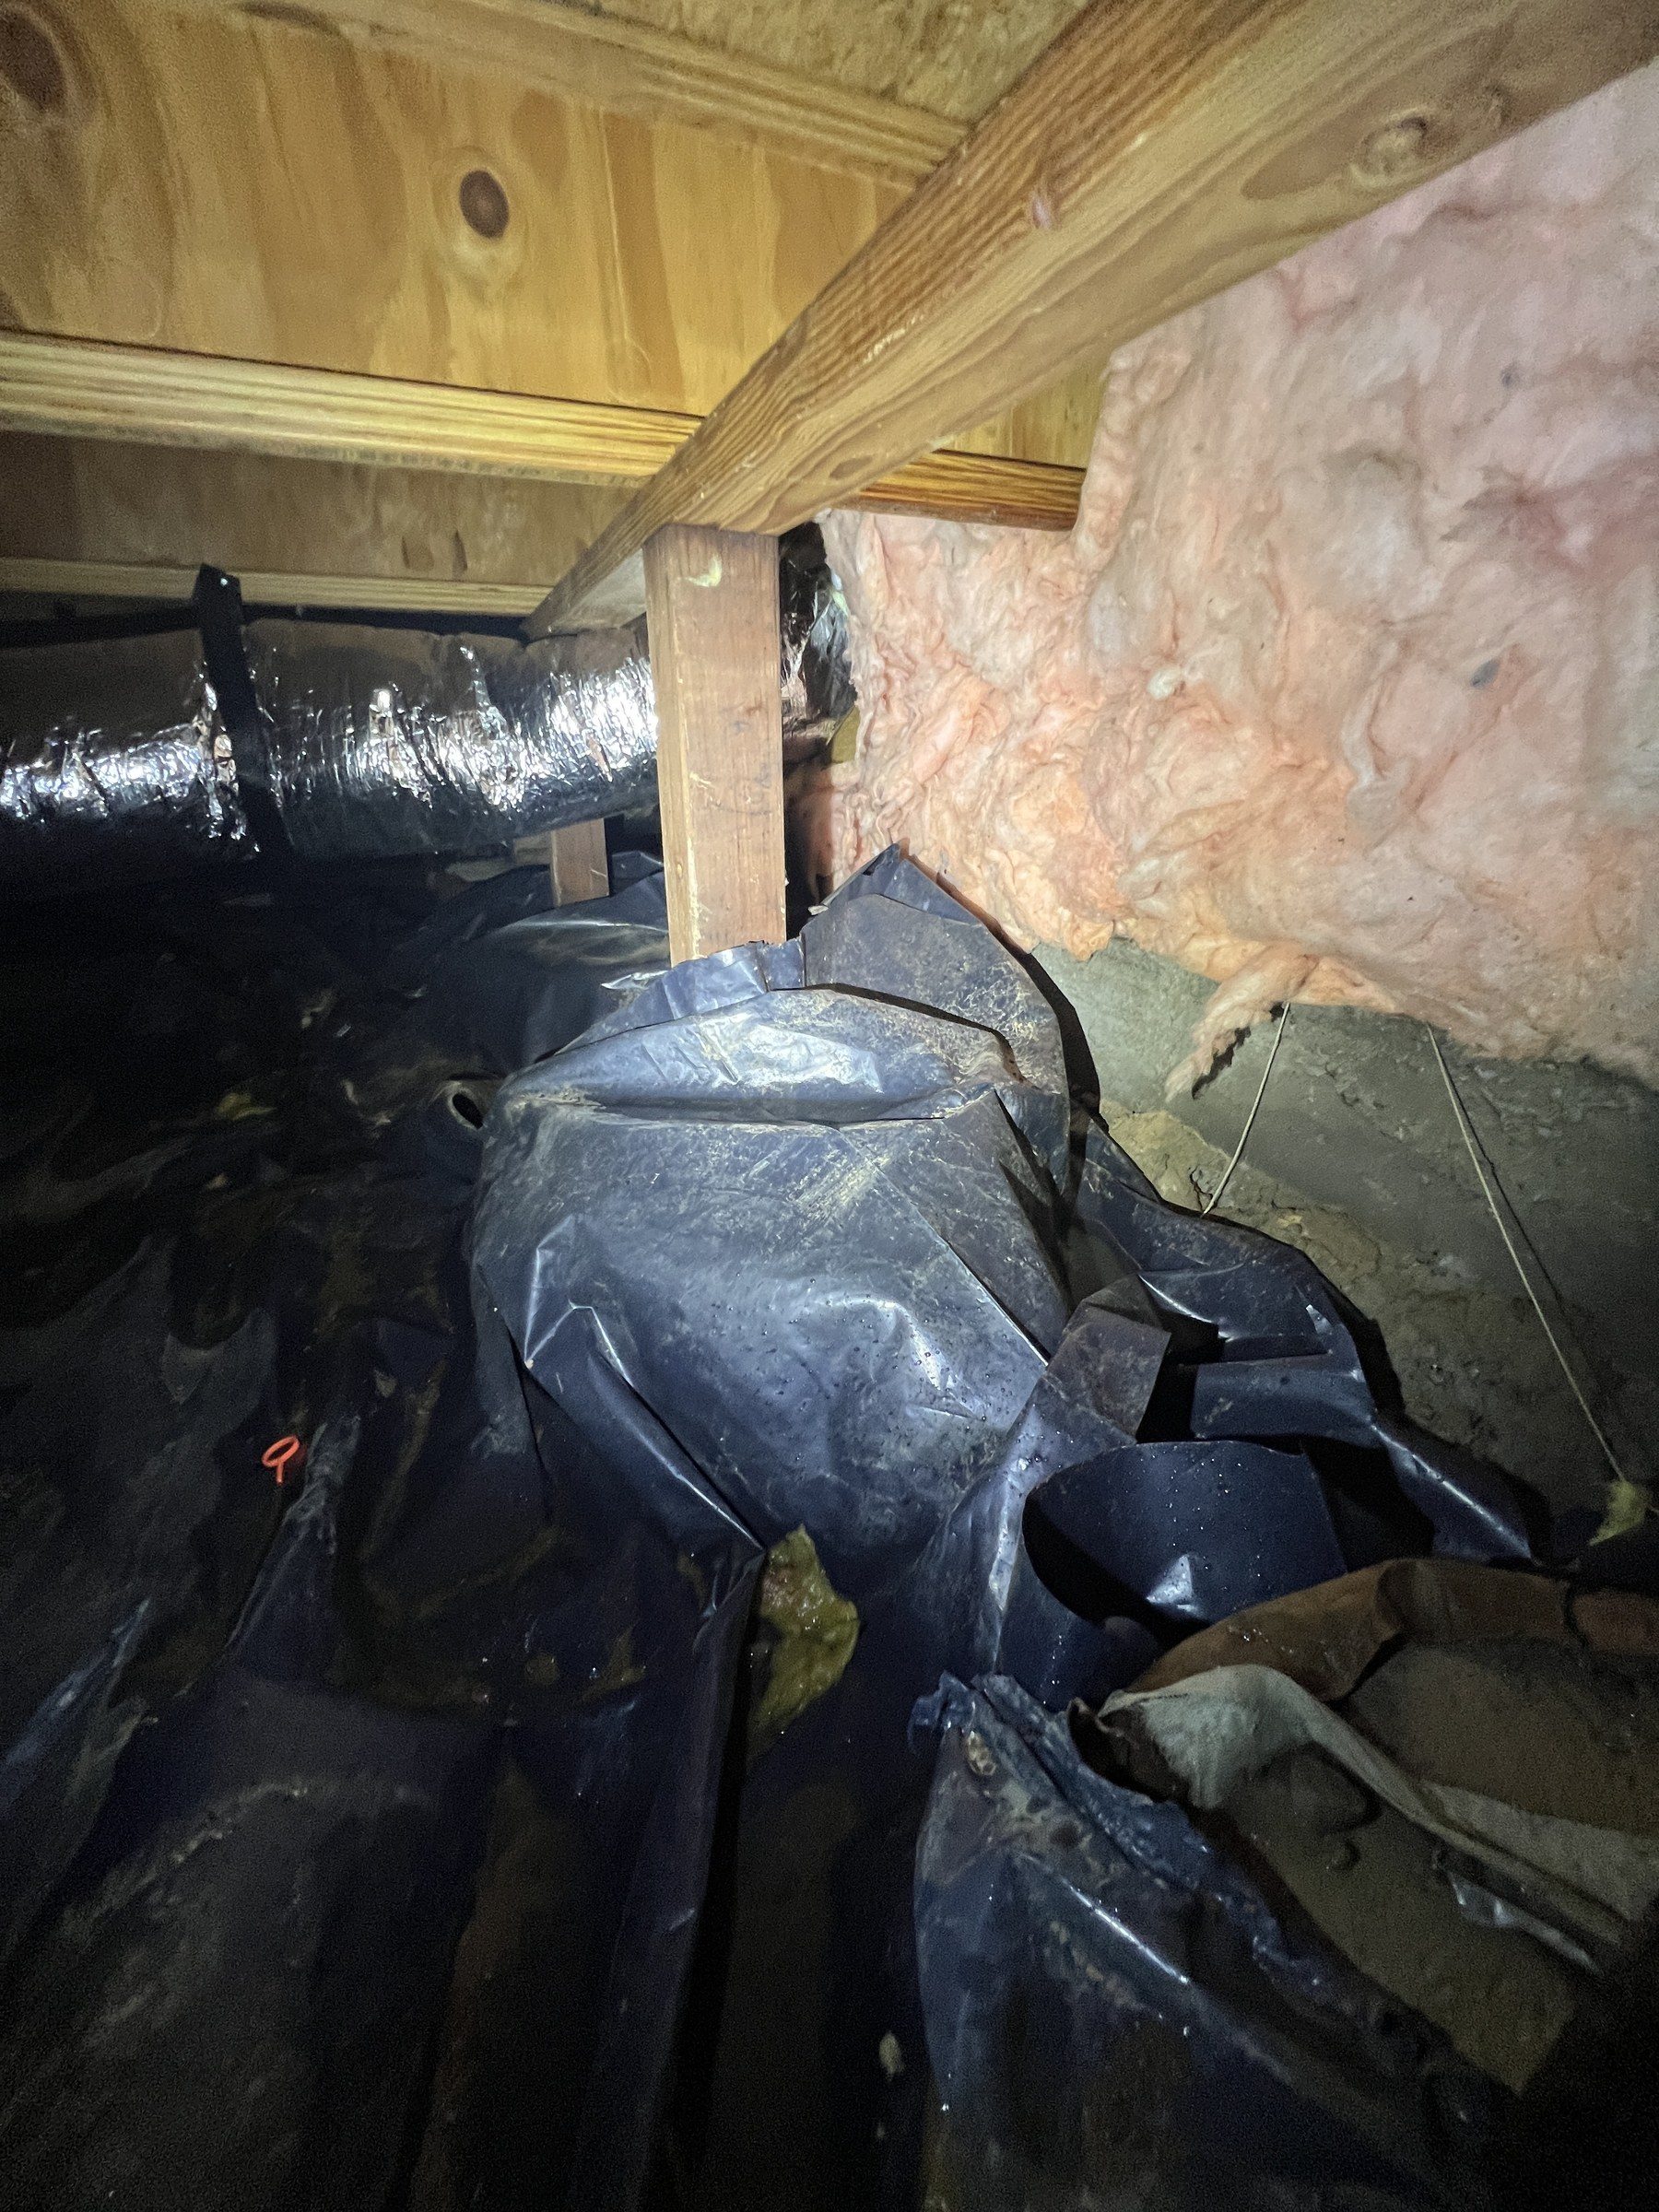
- Condensation, including window sweating and moisture on ductwork in a crawlspace.
- A failed or missing vapor barrier.
- Mold that was there when you bought the house. Coverage is for a loss during the policy period, not for a condition you inherited.
- Mold testing as a stand-alone service, in most cases. Carriers commonly pay for clearance sampling as part of an approved remediation scope and decline to pay for a homeowner's diagnostic test taken before there is a claim.
The mold sublimit, and where to find yours
Even when mold is covered, it is usually capped separately, and the cap is much smaller than your dwelling limit. This surprises people at the worst possible moment.
After the mold litigation wave of the early 2000s, carriers added a specific limitation to the standard homeowner form. On most policies today it appears as an endorsement titled something close to "Fungi, Wet or Dry Rot, or Bacteria," and it does two things: it caps what the carrier will pay for mold remediation and related testing, and it states the circumstances under which mold is covered at all.
We are not going to print a dollar figure here, because the number varies by carrier, by state, by form, and by whatever the homeowner selected at renewal, and a wrong number on this page could cost you real money. Look it up on your own paperwork instead. It takes about two minutes.
How to find yours in two minutes
Pull your declarations page, the two-page summary the carrier sends at renewal. Not the full policy booklet.
Scan the endorsement list for the words "fungi," "mold," "wet or dry rot," or "bacteria." It is usually a form number with a short title.
The limit sits next to it as a dollar amount, sometimes as a per-occurrence cap and sometimes as an annual aggregate. Note which.
Check whether a higher limit was available and declined. Many carriers offer a buy-up, and most people never knew it was an option.
If you cannot find it, call your agent and ask this exact question: what is my fungi and mold sublimit, per occurrence and annual. An agent can answer that in under a minute.
The sublimit applies to the mold portion of the work. The water damage that caused it is usually handled under the main dwelling coverage, which is why the way a scope is written and split matters, and why a line-item estimate is worth more than a lump sum.
The Idaho problem: irrigation water is flood
This is the one that catches Treasure Valley homeowners, and we would rather say it on the first phone call than at the end of the job.
The valley runs on gravity irrigation. The Boise Project fills roughly 1,500 miles of canals, laterals, and drains starting in the first days of April, and the shallow water table under a lot of this valley comes up with it. Crawlspaces that were dry all winter take standing water in May with nothing leaking anywhere in the building.
Water that arrives through the ground is surface water or flood under essentially every standard homeowner policy, and flood is excluded. There is no plumbing failure to point at, because there was never a plumbing failure. The mold that follows it in June is generally not a covered loss.
Standard flood insurance, which is a separate policy, has its own limitations on what it pays for below the lowest floor, and a crawlspace usually qualifies as that. Ask your agent specifically about crawlspace coverage before you assume a flood policy solves this.
There is a version of this that does get covered. If a sump pump fails and the resulting water is not ground water, or if a supply line in the crawlspace let go in the same week the canals charged, the cause of loss is different and the answer can be different. That is exactly why the source has to be documented rather than guessed at.
Canals charge in early April. Crawlspaces go wet in May. If that is the pattern in your house, the Crawlspace Guide covers what it is and what actually fixes it.
What protects the claim in the first 48 hours
Most mold claims that get reduced are not reduced because the carrier was unfair. They are reduced because nobody documented the loss while it was still documentable.
Stop the water and photograph the failure itself before anything is moved.
The failed fitting, the split pipe, the burst hose. That single photograph is the difference between a sudden accidental loss and an argument about how long it had been dripping.
Take video of every affected room before cleanup, with the date on it.
Ten minutes of phone video taken before anyone touches anything is worth more later than anything reconstructed from memory. Adjusters look at what can be shown.
Start drying immediately, and keep the readings.
Most policies require the homeowner to take reasonable steps to prevent further damage. Documented drying is how you prove you did. Mold begins colonizing wet organic material in roughly 24 to 48 hours, so waiting for an adjuster to arrive before drying can create the exclusion the carrier later applies.
Do not throw anything away until it has been photographed and listed.
Discarded material cannot be inspected. Cut samples of the carpet, pad, or flooring and keep them in a bag if the material has to go.
Ask the carrier for the claim number, the adjuster's name, and the mold sublimit, in writing.
Everything after that is easier when those three facts are on paper. Email is fine. A phone call with no record is not.
Ask for the scope line by line.
An adjuster can approve or dispute a line. A lump sum can only be accepted or refused, and it usually gets refused.
What goes in the file, whichever way it falls
Our job on a claim is evidence and scope. What was wet, how wet, what it took to fix, and what it cost. We write it in Xactimate line items because that is the format adjusters work in, and every line has a photo, a measurement, and a date behind it.
We state the cause of loss honestly, including when the honest answer is that this is ground water and it is not going to be covered. A claim built on the wrong cause of loss does not hold up, and the place it falls apart is usually after the work is done and the homeowner is holding the bill.
We are the contractor, not the carrier. We do not decide coverage and we will not tell you we can get something approved. What we can do is make sure the decision gets made on a complete file instead of an incomplete one.
- Cause of loss
- stated plainly, with the photograph that supports it
- Moisture readings
- at marked points, logged daily while equipment runs
- Affected area
- measured and mapped, not estimated from a doorway
- Scope
- Xactimate line items, mold work separated from water work
- Clearance
- by an independent inspector, billed by them, not by us
Questions we get about mold and insurance
Does homeowners insurance cover mold removal?
It depends on the cause of the water, not on the mold. Most policies cover mold that results from a sudden, accidental, covered water loss, up to a mold sublimit written into the policy. Most exclude mold from humidity, condensation, long-term seepage, ground water, or deferred maintenance. The way to find out is to identify and document the water source first, because that is what the adjuster is actually evaluating.
Does insurance cover mold from water damage?
Often, if the water damage itself was covered and the mold followed it. The common failure point is timing. If the water sat because nobody dried it, a carrier can argue the mold resulted from the delay rather than from the loss. Documented drying that started immediately, with readings, is the strongest protection against that argument. If the water damage was never covered, the mold from it generally is not either.
Does insurance cover mold in the attic?
Usually not. The most common cause of attic mold in this valley is house air condensing and frosting on cold roof sheathing, often because a bath fan was ducted into the attic instead of through the roof. That is a maintenance and ventilation problem, and carriers treat it as one. Attic mold that follows a sudden covered event, like wind opening the roof or an ice dam forcing water in, is a different conversation and is often covered up to the mold sublimit.
Does insurance cover mold in a crawl space?
Rarely, in the Treasure Valley. The usual cause here is ground moisture, a failed vapor barrier, or a water table that rises when the irrigation canals charge in April, and all three are excluded on a standard homeowner policy. A sudden pipe break under the house is a different cause of loss and is usually covered. This is why we put the source in writing before anyone files anything.
What is a mold sublimit?
A separate, smaller cap on what a policy will pay for mold remediation and related testing, applied on top of your regular coverage. On most policies it appears as an endorsement titled something close to "Fungi, Wet or Dry Rot, or Bacteria," and the dollar amount is on your declarations page. It varies by carrier and by what you selected at renewal, and many carriers sell a higher limit that most people never knew was available. Ask your agent for your per-occurrence and annual numbers.
Does insurance pay for mold testing?
Sometimes, as part of an approved remediation scope. Clearance sampling after remediation is commonly covered and commonly counted against the mold sublimit. A diagnostic test a homeowner buys before there is a claim is usually not reimbursed. Ask the adjuster directly whether sampling is included in the approved scope, and ask whether it comes out of the sublimit or the main limit.
Should I file a mold claim?
That is your call and it depends on the size of the loss against your deductible and your sublimit. One caution worth knowing: at some carriers a phone call describing a loss gets logged as a claim even if you decide not to pursue it. Before you describe the damage, ask directly whether the call opens a claim. We can tell you what the scope looks like and what it will cost before you decide.
My mold claim was denied. What now?
Read the denial letter and find the exact exclusion it cites, because everything after that follows from which one it is. If the denial rests on a factual claim about the cause or the duration, documentation can be submitted in response, and that is where readings, dated photos, and a written source statement matter. If you want representation, a licensed public adjuster or an attorney is who does that work in Idaho. We are neither, and we will not pretend otherwise. What we can do is hand you a complete file.
Do you bill my insurance company directly?
No. The claim stays in your name: the carrier pays you, and you pay us. What we hand over is the estimate in the format the adjuster works in and the complete documentation file, and you approve the number before any work starts.
Related
Find out what made it wet
The cause of loss decides the claim, and it is a readings question. Call and describe what you found. A person answers the phone, 24 hours a day.