Peak Home Plan · Treasure Valley homeownersAn inspection every year. Every dollar doubled.
Eighteen dollars a month. A technician puts instruments on your whole house once a year and writes up what they find, monitors sit in the places that flood first, and every dollar you pay in comes back doubled as credit toward repair labor and equipment.
- $18 a month, or the year up front
- The $279 Full Inspection included every year
- Every dollar of dues matched two to one into credit
- Moisture monitors in the house
$18/monthor $216 for the year, paid up front
The arithmetic
Every dollar of dues comes back as two dollars of repair credit, and it builds for as long as you stay a member.
| Year | Dues paid, total | Repair credit, total |
|---|---|---|
| Year 1 | $216 | $432 |
| Year 2 | $432 | $864 |
| Year 3 | $648 | $1,296 |
| Year 4 | $864 | $1,728 |
The Full Inspection is $279 on its own. The plan is $216 for the year and includes that visit, so the inspection costs $63 less inside the plan than outside it, and the whole $216 still comes back as $432 of repair credit. The monitors and the priority scheduling sit on top of that.
What the dues buy
Eight things. The first is the visit most people would pay for anyway. The second is one almost nobody in this trade offers.
- The Full Inspection, once a year
- Thermal imaging, moisture meters, LiDAR mapping, humidity readings, wall-cavity imaging, crawlspace and attic, odor source tracing, and a written digital report in your portal. The same $279 visit, every year, included in the dues.
- The annual visit can check a repair
- Ours or anyone else's. If a contractor fixed a leak, replaced a water heater, or dried out a crawlspace, the annual visit can put instruments on that work and tell you in writing whether it is holding. Most contractors will not check another contractor's work. We will.
- Dues matched two to one into repair credit
- Every dollar of dues comes back as two dollars of credit. Pay $216 in a year, accrue $432. It keeps building for as long as you stay a member, and it is sitting there the day something goes wrong.
- Credit covers Peak labor and equipment
- The labor our crews perform, the equipment and the drying days run on your job, and the specialty equipment and services a scope calls for. It does not cover materials or a third party's invoice. The full ledger of what it applies to and what it excludes is published lower down this page.
- Credit applies to money you are paying yourself
- On an insurance claim, the part you pay yourself is usually the deductible, and the credit can go toward it. It never touches any portion a carrier is paying. That is not fine print: applying a member discount to a carrier's line would be Peak and the customer jointly billing an insurer for a number neither of them intends to charge, and that is fraud.
- Moisture monitors placed in your house
- We put detection units in the spots that flood first and get noticed last: under the water heater, beneath sinks, in the crawlspace. The point is finding a leak the week it starts instead of the month you smell it.
- Your credit balance in the customer portal
- The same private page that shows a job in progress shows your plan: what you have paid in, what the match has built, and what it applies to. No statement to request and no number to take our word for.
- Priority scheduling for non-emergency work
- Members go to the front of the line for scheduled work: inspections, repairs, crawlspace jobs. Emergency response is 24/7 for everyone, member or not, and membership does not change it.
Track your credit in the portal
The same private page that shows a job in progress shows your plan the rest of the year: dues paid, credit built, and what it applies to. You never have to ask us what the balance is.
Client & partner login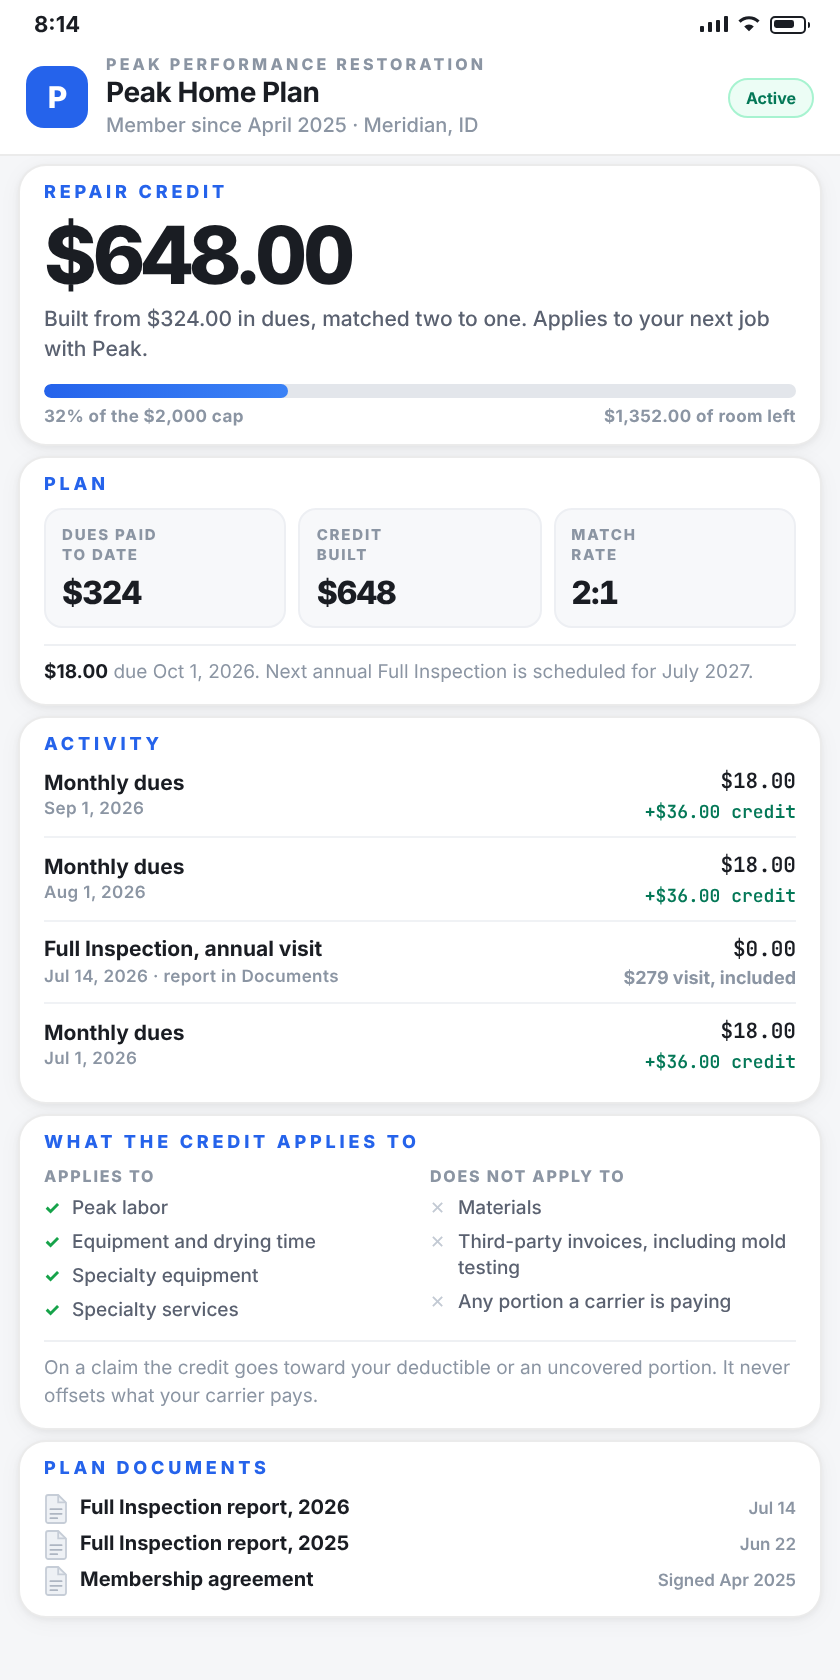
What the credit can and cannot pay for
Two columns, both complete. Nothing is held back for the estimate, and there is no line in either one you have to ask about.
It applies to
- Peak labor
- Equipment and drying time
- Specialty equipment
- Specialty services
It does not apply to
- Materials
- Third-party invoices, including mold testing and hygienist work
- Any portion an insurance carrier is paying
Repair credit is a discount on your own money. When an insurance carrier is paying for part of a job, the credit does not touch that part. Reducing a carrier-paid line by a member discount would mean Peak and the homeowner jointly presenting an insurer with a number neither of them intends to charge, and that is insurance fraud. The credit goes toward your deductible and anything else you are covering yourself, which is where it does you the most good anyway.
The Full Inspection fee is separate from all of this. It is credited in full against the job if you hire Peak, member or not. What the Full Inspection covers
How a member year goes
Nothing about the visit changes because you are a member. It is the same instruments and the same report. What changes is that it happens every year without you having to remember.
Enroll by phone.
Call, ask for the Home Plan, and choose monthly or the year up front. Dues start the month you enroll.
The annual visit gets scheduled.
The Full Inspection: instruments on the whole house, crawlspace and attic included, ending in the written report. If there is a repair you want checked, ours or someone else's, say so and it becomes part of the visit.
Credit builds as you pay.
Every dollar of dues comes back as two dollars of repair credit. The running balance is on your portal page, and you can ask for it at any time.
When work is needed, the credit comes off the labor and equipment.
You get a line-item estimate first, the same as any customer. The credit shows on it as a line, applied to the labor and equipment portion of what you are paying out of pocket.
Who this is for
A membership only makes sense for some houses and some owners. Both columns are written to be believed.
A good fit
- You own a house with a crawlspace in this valley.Treasure Valley crawlspaces get wet in irrigation season with nothing leaking. A yearly set of readings under the floor is the cheapest way to catch it early.
- You would pay for the inspection anyway.If you were going to book the $279 visit this year, the plan is $216 and includes it. You pay $63 less than the visit alone and hold $432 of repair credit at the end of the year.
- The house has had water before.A past leak, a past claim, a repair you were never fully sure about. The annual visit checks the old work with instruments and writes down what it finds.
- You want a number on the house every year.Readings, photos, and a report you keep. Useful the day you sell, the day you file a claim, or the day something smells wrong.
Not a good fit
- Water is on the floor right now.Call. That is emergency work, it is 24/7 for everyone, and no membership makes the truck arrive sooner.
- You want a faster emergency response.There is not one to sell. Everyone gets the same emergency line and the same crew. Priority scheduling applies to work that can be booked, not to losses in progress.
- You expect the credit to raise what insurance pays.It does not touch the carrier's side. It goes toward what you pay out of pocket, like the deductible. If you never pay out of pocket, the credit has nothing to apply to.
- You want a discount on materials.The credit covers labor and equipment only. Drywall, lumber, and flooring are billed the same either way.
- You would rather pay for one visit when you need it.That is fine. The Full Inspection is $279 whenever you want it, credited in full if you hire us for the work, and the free visit is free. There is no obligation to join.
Plan terms, in brief
What the plan is, in the fewest sentences that are still accurate. Full plan terms are provided at enrollment.
- $18 per month, or $216 for the year paid up front.
- Includes one Full Inspection per membership year, a $279 visit on its own.
- Every dollar of dues is matched with two dollars of repair credit. Credit caps at $2,000 total.
- Credit applies to Peak labor, equipment and drying time, specialty equipment, and specialty services on work you are paying for yourself. It does not apply to materials, to third-party invoices including mold testing and hygienist work, or to any portion an insurance carrier is paying.
- Priority scheduling applies to non-emergency work. Emergency response is not tiered.
- Full plan terms are provided at enrollment.
Questions we get about the plan
What does the Peak Home Plan cost?
$18 a month, or $216 if you pay for the year up front. Both come to the same $216 a year, and both are matched two to one into repair credit.
How does the repair credit work?
Every dollar of dues is matched with two dollars of credit. Pay $216 in a year and you have $432 of credit. It keeps building while you are a member. When Peak does work you are paying for yourself, the credit comes off the labor and equipment portion of the bill.
What can the credit be used on?
Peak labor, equipment and drying time, specialty equipment, and specialty services. Not materials, not third-party invoices such as mold testing or hygienist work, and not any portion an insurance carrier is paying. On a claim, the part you pay yourself is typically your deductible, and the credit can go toward that. The full ledger is published on this page.
Is the annual inspection the same as the $279 Full Inspection?
Yes. Same instruments, same crawlspace and attic, same written report. The plan includes it once a year.
Can the annual visit check work another contractor did?
Yes. Tell us what was done and where, and the visit puts instruments on it: moisture readings, thermal imaging, a look at the crawlspace or attic if that is where the work was. You get the result in writing. It works the same for our own past work.
Does membership get me faster emergency response?
No, and we would rather say that plainly than sell it. Emergency response is 24/7 for everyone who calls. Members get priority scheduling for work that can be booked ahead: inspections, repairs, crawlspace work.
Is the plan worth it if I only ever use the inspection?
You pay $216 a year for a $279 visit, so the inspection costs $63 less inside the plan than outside it. You also hold $432 of credit after year one. If you never need a repair, that credit sits unused and you still paid less than the visit alone would have cost. If you do need one, the credit pays for real labor.
How do I enroll?
Call (208) 391-5248 and ask for the Home Plan. Choose monthly or the year up front. Full plan terms are provided at enrollment.
Related
$18 a month
Call and ask for the Home Plan, then choose monthly or the year up front. The annual inspection gets scheduled, and the credit starts building the month you enroll. If you are not sure yet, the free Snapshot is a good first look at the house.